A Vote Held Open for Three Hours in 2003 Still Reads Your Tax Return
The Medicare bill passed at dawn after a 15-minute vote ran for three hours. Buried in it was a surcharge that looks back two years, which makes the next nine weeks unusual.
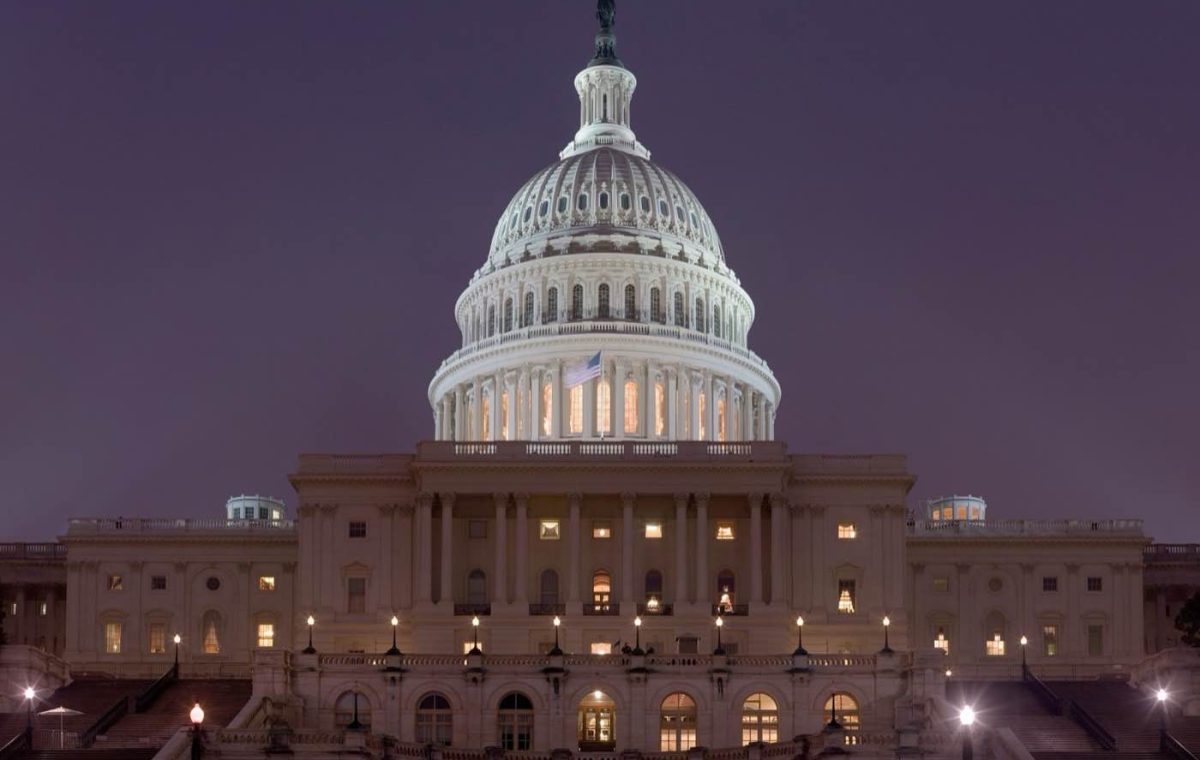
Shortly before three o’clock in the morning on Saturday, November 22, 2003, the United States House of Representatives was holding a vote open that should have taken fifteen minutes.
It had been open for nearly three hours. Leadership was working the floor. President Bush was placing phone calls from the White House — more than a dozen of them, to individual members, in the middle of the night. When it finally closed, the Medicare Prescription Drug, Improvement, and Modernization Act had passed 220 to 215. Senator Edward Kennedy was angry enough about the mechanics that he threatened to filibuster the thing in protest.
The fight that night was about the prescription drug benefit. That is what the arguing was for, and it is what the bill is remembered for: Part D arrived, along with the coverage gap that everyone eventually learned to call the donut hole.
Almost nobody on that floor was arguing about a second provision in the same bill. It created an income-related surcharge on Medicare premiums, it took effect in 2007, and it is now called IRMAA — the Income-Related Monthly Adjustment Amount.
The only part of Medicare that reads your tax return
Everything else about Medicare is blind to your finances. Part A and Part B cost what they cost. IRMAA is the exception: it looks at your income, and if it is above a threshold, it adds a surcharge to your Part B and Part D premiums for the year.
Two features of it cause nearly all the confusion.
The first is the lookback. IRMAA does not read this year’s income, because this year’s income does not exist yet as a filed return. It reads the return from two years earlier. So the premium you will pay in 2027 was determined by what you reported for 2025. And the premium you will pay in 2028 is being determined right now, by the 2026 return you have not filed yet.
That two-year gap is why the letter feels arbitrary when it arrives. The cause and the consequence are separated by twenty-four months, and by the time the bill shows up most people have genuinely forgotten what they did.
The second feature is that it is a cliff rather than a ramp. Cross a bracket threshold by a single dollar of income and the full surcharge for that bracket applies, for the entire year. There is no gradual phase-in that softens the edge.
Three things are stacked in the same nine weeks
Which brings us to why this is a timely subject rather than a piece of trivia about a long night in 2003.
Four separate rules are currently pointed at the same number — your modified adjusted gross income for 2026 — and the year ends on December 31.
IRMAA. Your 2026 income sets your 2028 Medicare premiums, with Part B projected to reach $209.50 a month before any surcharge.
The senior deduction. The temporary $6,000 deduction for taxpayers 65 and older, available for tax years 2025 through 2028, begins phasing out above $75,000 of modified adjusted gross income for a single filer and $150,000 for a married couple filing jointly. It disappears entirely above $175,000 and $250,000. Both spouses in a couple can claim it separately if both are 65 or older. It is a deduction against taxable income, not a check, and a surprising number of people have been told otherwise.
Required minimum distributions. Anyone 73 or older generally has to take a distribution from a traditional retirement account by December 31, and a distribution is income. Those who turned 73 this year have until April 1 of next year for the first one only.
The qualified charitable distribution. For 2026, up to $111,000 per person can go directly from an IRA to a qualified charity. It can satisfy the required distribution, and it does not pass through taxable income on the way. A married couple with separate IRAs can each do one. The funds have to be received by the charity by December 31 — in transit does not count.
Four rules, one number, nine weeks.
What this means if the nest egg can’t be replaced
We are a publication, not an advisory, and we are not going to tell you to do any of the things described above. We do not know your tax situation, your other income, your health, or your spouse’s, and anyone who offers you a recommendation without knowing those things is not helping you.
What we will say is this. For most of the year, your modified adjusted gross income is a historical fact — it is whatever it already turned out to be. In the last stretch of a calendar year it is briefly something else: a figure still capable of being influenced by decisions about timing, because distributions, conversions, charitable transfers and the realization of gains all have dates attached to them.
That is not a strategy. It is an arithmetic property of a calendar. But it is the reason that a conversation with whoever prepares your return is worth considerably more in November than in March, and why the people who have that conversation in March are usually hearing about an opportunity that closed.
One thing to do this week
Pull last year’s tax return and find your adjusted gross income on the front page. Then find the IRMAA brackets for the coming year — they are published by Medicare and easy to locate — and note where your number sits relative to the nearest threshold.
You are not making a decision. You are establishing whether you are anywhere near an edge, because everything above matters enormously to people near a threshold and very little to everyone else. Knowing which one you are takes about ten minutes.
The drug benefit took three hours of arm-twisting and made every front page. The surcharge went through in the same bill with no argument at all, and it is the part that reads your mail.