The First Social Security Check Was $22.54. She Cashed One for 35 Years.
Ida May Fuller collected for three and a half decades without a single automatic raise. What replaced the politics in 1975 is the formula that just produced 3.6 percent.
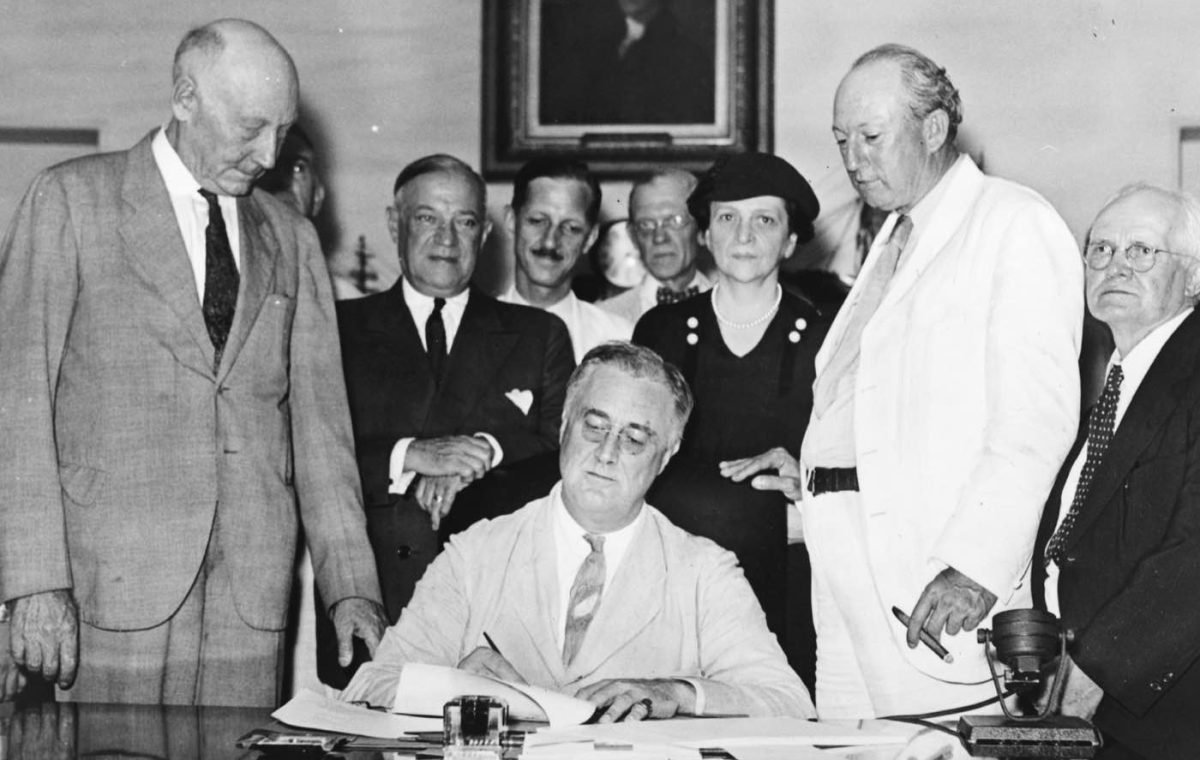
In January 1940, a retired legal secretary in Ludlow, Vermont, walked to the post office and collected an envelope containing check number 00-000-001. It was made out to Ida May Fuller for $22.54.
She had paid $24.75 into the system over three years of work. The usual reason people tell this story is the arithmetic that followed: Fuller lived to 100, died on January 31, 1975, and collected $22,888.92 in benefits against that $24.75 in taxes.
That return is the famous part. It is not the interesting part.
The interesting part is that for almost the entire span of her retirement — 35 years, the same 35 years she spent cashing those checks — Social Security had no automatic raise of any kind.
When a raise required an act of Congress
Benefits went up only when Congress passed a law saying so. And Congress did, repeatedly: a 77 percent increase in 1950, 12.5 percent in 1952, 13 percent in 1954, 7 percent in 1958, 13 percent in 1967, 15 percent in 1969.
Read those years again. They cluster where you would expect them to cluster. A raise was not a calculation; it was a decision, made by people who had to stand for election, in a year when standing for election was on their minds.
Which meant a retiree’s income was tied to the political calendar rather than to the price of anything. In a quiet year you got nothing, no matter what had happened at the grocery store.
That ended in 1972. Senator Frank Church of Idaho attached a rider to the Social Security amendments that did two things at once: it granted an immediate 20 percent increase, and it made future increases automatic, tied to an inflation index. The first automatic adjustment was paid in 1975 — 8 percent.
Ida May Fuller died the same year the automatic era began. She never received one.
What the formula actually measures
The raise stopped being a decision and became a formula, which was the entire point and was unambiguously an improvement. But a formula has to measure something specific, and the something chosen was the Consumer Price Index for Urban Wage Earners and Clerical Workers.
Read that name slowly. It is an index built to track the spending of working people — a household with a commute, a mortgage, growing children, and a paycheck.
A retired household does not buy that basket. It spends a substantially larger share of its money on medical care and on keeping a house warm and lit, and a smaller share on getting to work and raising children. The index is not wrong. It is measuring somebody else.
Which brings us to October 14
On October 14, the Social Security Administration announced that benefits will rise 3.6 percent in 2027. It is the largest adjustment in five years, it reaches roughly 72 million people, and it works out to about $75 a month on an average retirement benefit.
Then the subtraction starts. Medicare’s Part B premium is projected to rise to $209.50 a month, up $6.60. The Part B deductible is projected at $292, up from $283. For most people the Part B premium comes directly out of the Social Security payment before it is deposited, which is why the raise and the premium are not two separate pieces of news.
None of that is a scandal, and we are not going to pretend it is one. A 3.6 percent adjustment in a year of moderate inflation is the formula doing exactly what it was built in 1972 to do. The point is narrower: the formula was built to track a wage earner’s costs, and it has never claimed to track yours.
What this means if the nest egg can’t be replaced
Here is the part that matters for anyone living on a retirement account they have no way of rebuilding.
Social Security is the only piece of your income that adjusts itself every year, automatically, for the rest of your life. An IRA does not do that. A 401(k) balance does not do that. A certificate of deposit does not do that.
So the share of your monthly income that carries built-in inflation protection is, in effect, fixed on the day you retire — and it is a share, not a dollar amount. If the costs that grow fastest in your household are the ones the index underweights, the protected portion quietly covers less of your life each year, even in a year when the raise arrives on schedule and does what it promised.
That is not an argument for alarm, and it is not an argument for buying anything. It is an argument for knowing one number.
One thing to do this week
Find the percentage. Add up what Social Security pays your household in a year, divide it by your total annual income from all sources, and write the result on a piece of paper with today’s date on it.
That percentage is how much of your income has a raise built into it. Everything else is a number you are responsible for. Most people have never calculated it, and nearly everyone is surprised by it in one direction or the other.
Ida May Fuller spent 35 years waiting on Congress for a raise. You get one automatically now, which is the better arrangement by a wide margin. It is simply worth knowing how much of your life it covers.